PsiMVLogNormal Distribution
PsiMVLogNormal (µ,∑)
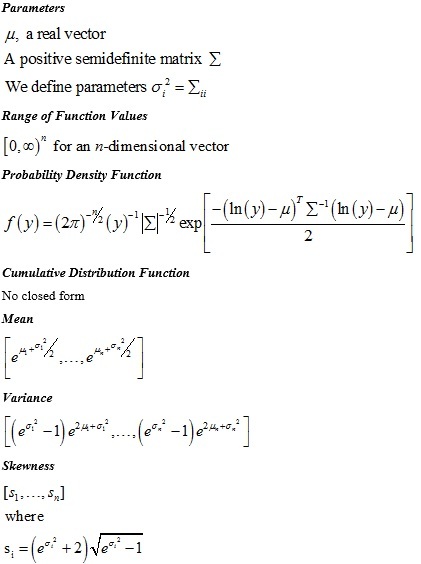
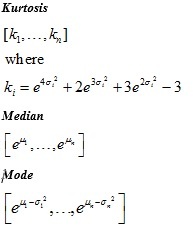
PsiMVLogNormal (µ,∑) is a multivariate distribution that returns a vector of random variables that are lognormally distributed, with mean values specified by the vector µ, and covariance values specified by the matrix ∑. This is a generalization of the PsiLogNorm2 distribution to higher dimensions. A variable vector y = [y1,…,yn] has a multivariate LogNormal distribution if and only if the variable vector [ln(y1),…,ln(yn)] has a multivariate Normal distribution.
PsiMVLogNormal returns an array of sample data; to use it, you must ‘array-enter’ a formula using this function. For example, you might select cells A1:A5, type a formula such as =PsiMVLogNormal(B1:B5,C1:G5), and press Ctrl + Shift + Enter. The formula will then appear in all five cells A1:A5 as {=PsiMVLogNormal(B1:B5,C1:G5)}. On each Monte Carlo trial, the function will return 5 sample values.